


Authors: Bob Gertie, CLTC — Life, DI, LTC, Annuities | Debbie Gertie — Property & Casualty
My husband, Bob, and I recently attended a golf tournament in the Denver metro area to watch our youngest daughter compete. While there, we noticed a crew removing the roof of a nearby home. What we saw was striking: more than six sections of roof decking had rotted beneath the original asphalt shingles — soft enough in places that the roofers nearly fell through. That was only the side of the house facing the golf course; we could not even see the front of the property.
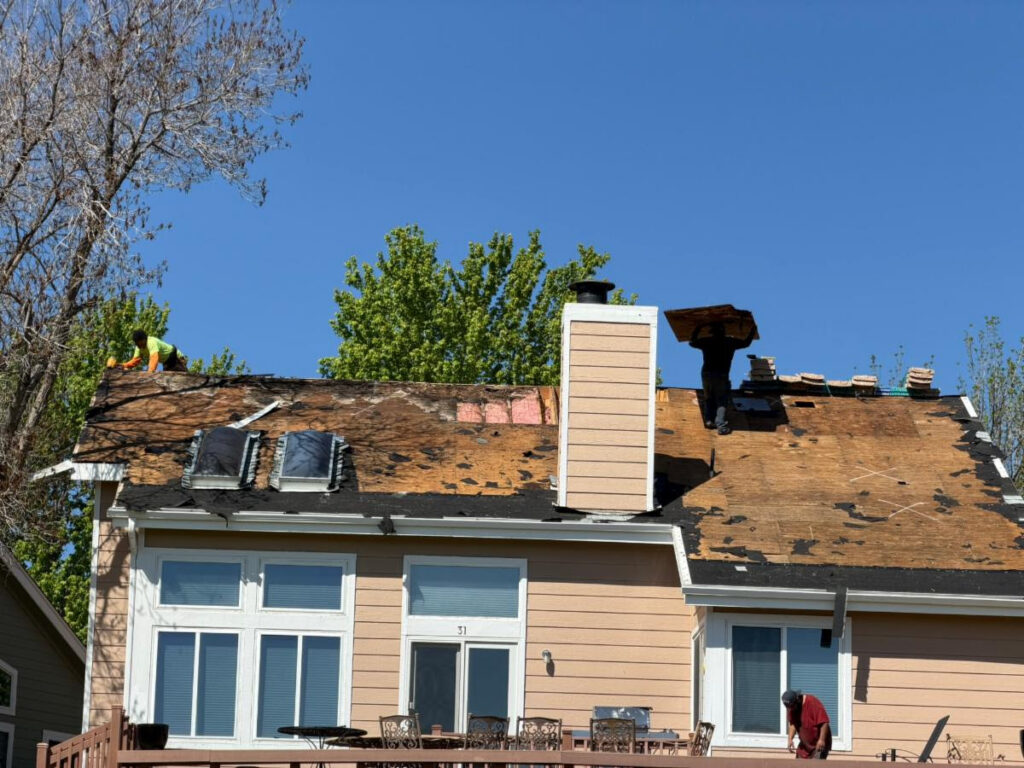
That roof should have been replaced years earlier under general maintenance practices. The homeowner most likely has interior leak damage they may not even have been aware of, and is almost certainly paying — or will soon pay —more than necessary for homeowners insurance coverage on a roof of that age and condition, if insurable at all.
It is a good reminder of something we see regularly in our work with affluent clients: a proper roof replacement is one of the most overlooked opportunities to lower a client’s insurance costs — but only if it is funded and reported correctly.
Two Recent Examples
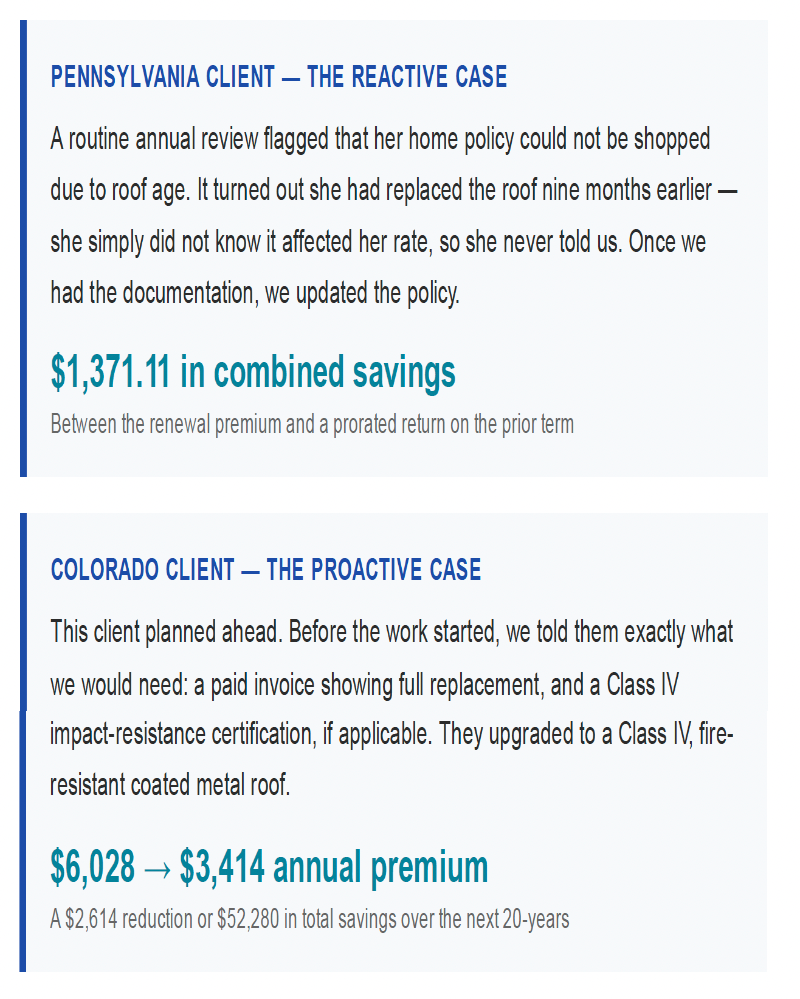
Same event — a new roof — handled two different ways, with two very different outcomes for the client.
ABOUT YOUR P&C RESOURCE
Debbie Gertie has been with Advisor Insurance Resource® since 2008 and is one of the few national experts in property and casualty insurance for high-net-worth households. As an independent broker licensed across most of the country, she is known for placing the most difficult home, auto, and liability cases by working directly with the top carriers in the affluent market. She regularly speaks at financial planning conferences and works closely with planning groups — including women-focused financial planning organizations— to help advisors stay ahead of issues like this one for their clients.